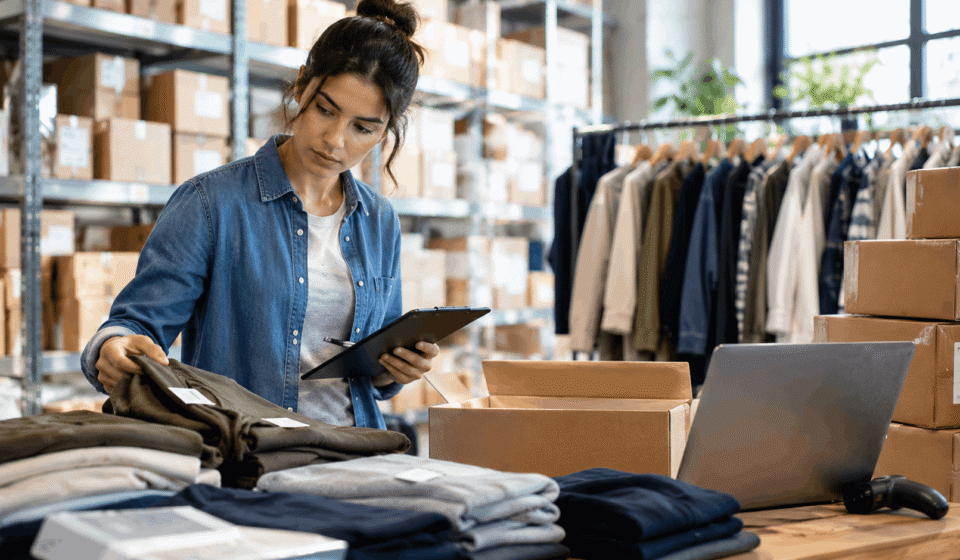

If you’re asking what do deadstock mean for your business, the short answer is this: deadstock (also written as “dead stock”) is inventory you’re holding that has stopped selling and probably won’t sell at full price again. It’s product that’s still sitting on a shelf or in a warehouse, tying up cash you spent buying it, while generating no revenue in return.
That’s the definition that matters if you’re running a retail, ecommerce, or wholesale business. There’s a second, unrelated use of the same word worth flagging up front so you’re not confused by conflicting search results: in sneaker and streetwear resale, “deadstock” describes a brand-new, unworn item still in its original packaging, and it’s treated as a selling point rather than a problem. This guide covers the retail inventory meaning, since that’s the one with real financial consequences for a business.
What Counts as Deadstock
Deadstock typically refers to items that haven’t sold within a set window, often six to twelve months depending on your industry, though the exact timeline varies by product category and how fast your normal inventory turns over. Common causes include:
- Seasonal or trend-driven products that missed their selling window
- Items discontinued by a supplier or manufacturer
- Overordering based on demand forecasts that didn’t hold up
- Products damaged, defective, or returned in unsellable condition
- SKUs that never found product-market fit in the first place
None of these causes are unusual on their own. Every business that holds physical inventory ends up with some deadstock eventually. The problem is what happens when it’s not identified and dealt with.
Why Deadstock Actually Costs You Money
Deadstock isn’t just inventory sitting quietly on a shelf. It ties up capital you could have spent on products that actually sell, and it continues costing you in storage space, insurance, and staff time even while generating zero revenue. Shopify’s own glossary entry on dead stock makes the same point directly: it’s inventory that hurts more than just your stock count, since it also distorts your ability to see which products are genuinely performing.
There’s also an accounting dimension worth understanding, even in general terms. Under U.S. tax rules, inventory that can’t be sold at normal prices due to damage, style changes, or similar causes falls under what the IRS calls “subnormal goods.” IRS Publication 538, which covers accounting periods and inventory valuation methods, explains that these goods should be valued at their bona fide selling price minus the direct cost of disposing of them, regardless of which inventory valuation method you otherwise use. This is a general accounting rule, not individualized tax advice, and how it applies to your specific inventory and books should be confirmed with your accountant, since the details depend on your valuation method and how your business classifies the goods.
How to Tell Deadstock From Slow-Moving Inventory
These two get confused often enough to be worth separating clearly. Slow-moving inventory still sells, just more slowly than you planned when you ordered it. It’s not dead, it’s just tying up cash and shelf space longer than ideal. Deadstock has effectively stopped selling entirely, whether because the product was discontinued, the trend passed, or a newer version made the old one obsolete.
The distinction matters because the fix is different. Slow-moving inventory often just needs a pricing adjustment or better placement. Deadstock usually needs a more decisive move, since waiting longer rarely improves the outcome.
What to Do With Deadstock Once You’ve Identified It
Once inventory is genuinely dead rather than just slow, a few options are worth considering, roughly in order of how much value you recover:
Discount and clearance sales. The most straightforward option, though margins on these sales are usually thin or negative once you account for the original cost.
Bundling with better-selling products. This moves deadstock alongside a product that’s still in demand, which can recover more value than a standalone clearance price.
Returning to suppliers. Some supplier agreements include return or buyback terms for unsold inventory. It’s worth checking your original purchase terms before assuming this isn’t an option.
Liquidation sales to secondary buyers. Liquidation companies and discount retailers will often buy deadstock in bulk at a steep discount, which recovers less per unit but clears the inventory quickly and in one transaction.
Donation. For inventory that’s genuinely unsellable even at deep discount, donating it can offer a tax deduction depending on your entity type and the donation’s documented value, though the specific deduction rules depend on your business structure and should be confirmed with a tax professional before you rely on them.
Avoiding Deadstock in the First Place
The businesses that deal with deadstock least aren’t the ones that never make a bad ordering decision. They’re the ones that catch it early through regular inventory reviews rather than discovering a pallet of unsold product a year later during a stock count. A recurring inventory aging review, looking specifically at what hasn’t moved in your defined window, catches emerging deadstock while there’s still time to discount it or bundle it rather than eating the full loss later.
Demand forecasting based on actual sell-through data, rather than gut instinct or the previous year’s ordering pattern, also reduces how much new deadstock gets created going forward. This matters more for seasonal or trend-sensitive product categories, where the gap between “we think this will sell” and “this actually sold” tends to be widest.