
Different types of business risk Every business decision carries some chance that things won’t go as planned. Business risk is the general term for that exposure: anything that could keep a company from hitting its financial goals or threaten its ability to keep operating. The useful next question isn’t whether risk exists (it always does) but which category a given risk falls into, because the category usually determines who owns it, how it gets measured, and what a reasonable response looks like.
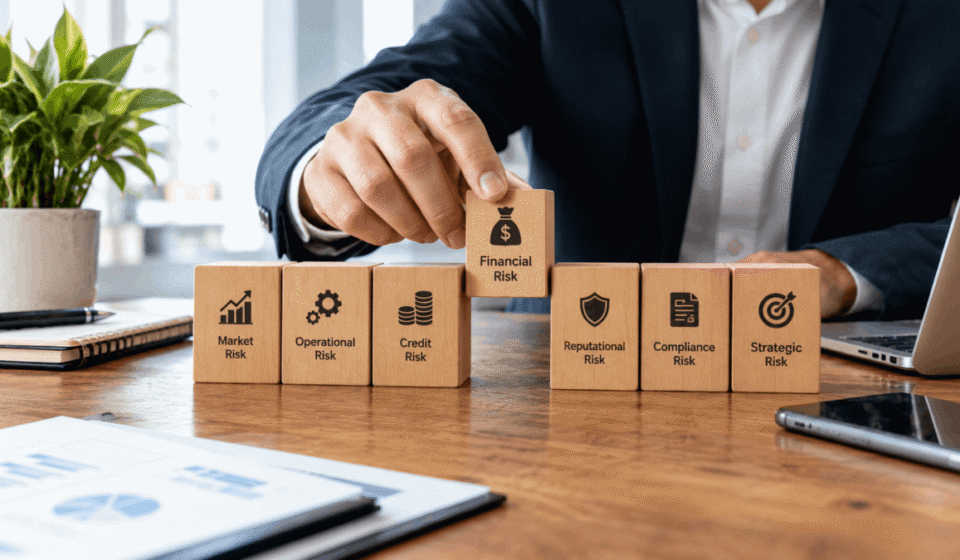
Most risk frameworks group business risk into a handful of recurring categories. The COSO Enterprise Risk Management framework, one of the most widely used risk frameworks in the world, organizes risk around an organization’s strategic, operational, reporting, and compliance objectives, and most practical small-business guidance adds reputational and external or hazard risk as distinct categories worth tracking on their own. None of these categories are airtight. A single event, a data breach, for example, can trigger operational, compliance, financial, and reputational consequences all at once. The value of separating them isn’t precision for its own sake. It’s that each category tends to need a different owner, a different detection method, and a different kind of response.
Strategic Risk
Strategic risk is the exposure that comes from the big decisions a company makes about direction: what markets to enter, what to build, who to compete against, and what to bet the business on. It’s distinct from execution risk. A company can execute a strategy flawlessly and still lose, because the strategy itself was built on assumptions that turned out to be wrong, a market that didn’t materialize, a competitor that moved faster, or a customer preference that shifted underneath the plan.
The standard way to surface strategic risk before it becomes a crisis is a structured look at both the company’s internal position and its external environment, using tools like SWOT, PESTEL, and Porter’s Five Forces. Business Atlas Pro’s guide to running a business strategic diagnosis walks through how that assessment works in practice. Strategic risk also tends to compound when a company sets a plan once a year and never revisits it. Building a habit of checking assumptions against what’s actually happening, sometimes called strategic learning, is one of the more effective ways smaller companies catch a strategic risk early instead of discovering it after a quarter of declining results.
Operational Risk
Operational risk covers the day-to-day mechanics of running the business: the people, processes, systems, and physical assets a company depends on to deliver its product or service. A supplier that misses a shipment, a key employee who leaves without documented processes behind them, a point-of-sale system that goes down during a busy weekend, and a production error that ships a defective batch are all operational risks. They tend to be more frequent and lower-severity individually than strategic risk, but they add up, and a company with no documented processes is exposed to the same failure repeating every time institutional knowledge walks out the door.
Operational risk is also the category most directly tied to business continuity. A hazard event, a fire, a flood, a regional power outage, becomes an operational crisis the moment it interrupts the processes the business runs on. That overlap is why disaster preparedness and operational risk management are usually planned together rather than as separate exercises.
Financial.Risk
Financial risk is exposure tied to the money itself: cash flow gaps, too much debt relative to what the business can service, customer concentration (a handful of clients making up most of revenue), currency or interest rate exposure for companies that carry variable-rate debt, and the simple risk of running out of cash before revenue catches up with expenses. Financial risk is often the lagging indicator of problems that started somewhere else. A strategic misstep or an operational failure usually shows up in the financial statements eventually, which is one reason financial risk gets tracked closely even by companies that don’t have a formal enterprise risk process: it’s often the clearest early signal that something upstream needs attention.
Compliance and Legal Risk
Compliance risk is the exposure that comes from failing to meet a legal, regulatory, or contractual obligation, whether that’s employment law, licensing requirements, data privacy rules, industry-specific regulation, or the terms of a contract with a customer or vendor. This category deserves particular attention because the consequences are rarely limited to a fine. A compliance failure can trigger litigation, void insurance coverage, or damage a relationship with a regulator that the business needs to stay operational.
Compliance risk also varies significantly by industry and jurisdiction, so a checklist built for one type of company or one state often misses obligations specific to another. Businesses navigating a specific compliance question, worker classification, licensing, data handling, are better served working with an attorney or compliance professional familiar with the relevant jurisdiction than relying on a general overview.
That downstream nature makes reputational risk hard to manage in isolation. A company that treats reputation management purely as a communications function, without fixing the underlying operational or compliance issue that caused the damage, tends to see the same problem resurface.
External and Hazard Risk
External risk covers events largely outside a company’s control: natural disasters, macroeconomic shifts, pandemics, supply chain disruptions caused by geopolitical events, and broad changes in the regulatory or competitive landscape. The Small Business Administration’s Business Resilience Guide, released for small business owners preparing for and recovering from disasters, covers documenting essential operations, identifying dependencies on key vendors and partners, and building financial readiness before a disruption hits. The guide is worth reading directly for any business owner who hasn’t formally assessed disaster preparedness, since the archived SBA release lays out what a resilience plan should cover in more detail than a general overview can.
External risk is the category businesses can’t eliminate, only prepare for. The goal isn’t to prevent the event; it’s to shorten how long recovery takes and limit how much damage the business absorbs before it’s back to normal operations.
A Practical Way to Categorize Risk
A useful starting exercise for a small or mid-sized company is a simple risk log rather than a formal enterprise risk program, which most smaller businesses don’t need. For each risk identified, note the category it falls into, who inside the company would notice it first, what the realistic impact would be if it happened, and what one step would reduce either the likelihood or the impact. This mirrors the approach the FDIC and SBA’s joint Money Smart for Small Business risk management module takes, which walks owners through identifying internal and external risk factors and conducting a systematic risk assessment before building a response plan.
| Risk category | What it covers | Typical early signal | Who usually owns it |
|---|---|---|---|
| Strategic | Direction, market position, competitive assumptions | Slowing growth, shifting customer demand | Owner or leadership team |
| Operational | People, processes, systems, physical assets | Missed deadlines, repeated errors, single points of failure | Operations or department managers |
| Financial | Cash flow, debt, revenue concentration | Tightening margins, late payments, customer concentration | Owner, controller, or accountant |
| Compliance | Legal, regulatory, and contractual obligations | Upcoming filing deadlines, new regulation in the industry | Owner or legal counsel |
| Reputational | Public standing, customer trust | Negative reviews, repeat complaints on the same issue | Owner or customer-facing leadership |
| External | Disasters, macro shifts, supply disruption | Vendor instability, regional weather patterns, economic indicators | Owner, with input from insurance and legal advisors |
The table isn’t meant to be exhaustive. It’s a starting structure a business owner can adapt, since the specific risks that matter most will differ by industry, size, and stage of the company.